


“I have to brainstorm while grieving,” says Ana Juan, whose cover, “Reflections,” commemorates the tenth anniversary of 9/11. “Since I’m an emotional person, I discover things about myself I never imagined before.”
In its quiet beauty, Juan’s image evokes both the reflecting pools at soon-to-be-opened Ground Zero Memorial and the black-on-black cover that The New Yorker published in the aftermath of 9/11.


ΜΟREThe Case Against Rating Agencies
By MICHAEL HUDSON
In today’s looming confrontation the ratings agencies are playing the political role of “enforcer” as the gatekeepers to credit, to put pressure on Iceland, Greece and even the United States to pursue creditor-oriented policies that lead inevitably to financial crises. These crises in turn force debtor governments to sell off their assets under distress conditions. In pursuing this guard-dog service to the world’s bankers, the ratings agencies are escalating a political strategy they have long been refined over a generation in the corrupt arena of local U.S. politics.
Why ratings agencies favor public selloffs rather than sound tax policy: The Kucinich Case Study
In 1936, as part of the New Deal’s reform of America’s financial markets, regulators forbid banks and institutional money managers to buy securities deemed “speculative” by “recognized rating manuals.” Insurance companies, pension funds and mutual funds subject to public regulation are required to “take into account” the views of the credit ratings agencies, provided them with a government-sanctioned monopoly. These agencies make their money by offering their “opinions” (for which they have never been legally liable) as to the payment prospects of various grades of security, from AAA (as secure government debt, the top rating because governments always can print the money to pay) down to various depths of junk.

 Madonna, New York City, 1982
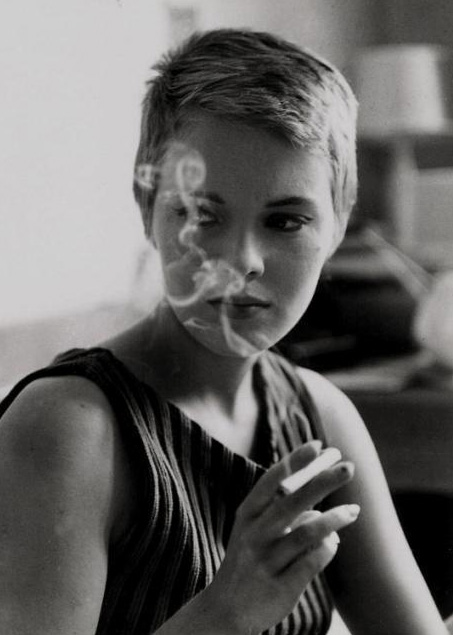
The exquisitely beautiful Jean Seberg in BREATHLESS (1960)

BREATHLESS (1960)

Anouk Aimée in Jacques Demy's LOLA (1961)

Francois Truffaut filming STOLEN KISSES (1968) on location

Truffaut with Françoise Dorléac on the set of THE SOFT SKIN (1964)

Jean Luc Godard (left) filming UNE FEMME EST UNE FEMME (1961)
Nouriel Roubini is a mainstream economist who teaches at New York University and may be best known as one of the early predictors of the '08 crash.
He is no Marxist.
But in an interview with the Wall Street Journal, Roubini admitted that Marx was right about Capitalism and raised the possibility that Capitalism is destroying itself in the way Marx outlined more than a century and a half ago.
WSJ: So you painted a bleak picture of sub-par economic growth going forward, with an increased risk of another recession in the near future. That sounds awful. What can government and what can businesses do to get the economy going again or is it just sit and wait and gut it out?Roubini: Businesses are not doing anything. They're not actually helping. All this risk made them more nervous. There's a value in waiting. They claim they're doing cutbacks because there's excess capacity and not adding workers because there's not enough final demand, but there's a paradox, a Catch-22. If you're not hiring workers, there's not enough labor income, enough consumer confidence, enough consumption, not enough final demand. In the last two or three years, we've actually had a worsening because we've had a massive redistribution of income from labor to capital, from wages to profits, and the inequality of income has increased and the marginal propensity to spend of a household is greater than the marginal propensity of a firm because they have a greater propensity to save, that is firms compared to households. So the redistribution of income and wealth makes the problem of inadequate aggregate demand even worse.
Karl Marx had it right. At some point, Capitalism can destroy itself. You cannot keep on shifting income from labor to Capital without having an excess capacity and a lack of aggregate demand. That's what has happened. We thought that markets worked. They're not working. The individual can be rational. The firm, to survive and thrive, can push labor costs more and more down, but labor costs are someone else's income and consumption. That's why it's a self-destructive process.
The full interview is here.
The portion where Roubini talks about Marx and excess capacity is here.

I say incurable. This is the diagnosis of an irreversible disease. The corruption and collapse of the rule of law, in the financial sphere, is basically irreparable. It’s not just that restoring trust takes a long time. It’s that under the new technological order in this field, it can not be done. The technologies are designed to sow and foster distrust and that is the consequence of using them. The recent experience proves this, it seems to me. And therefore there can be no return to the way things were before. In other words, we are at the end of the illusion of a market place in the financial sphere.
Let me take this analysis and bring it to bear momentarily on Europe. We speak in a common place way these days of the Greek crisis, the Irish crisis, the Portuguese crisis and so forth, as though these were distinct financial events. This fosters the impression that each can be resolved by appropriate agreement between the creditors, headquartered in Frankfurt, Brussels, Berlin, Paris, and the debtors taken one by one. Good behavior, taking the form of a suitable austerity will be rewarded by a return to normal credit conditions and market access. That, at least, is the official presumption. The financial market, in this imagery, is severe but fair, she cracks the whip on the profligate but praises and rewards the prim.
But that Greece has a weak tax system and a big civil service was hardly news. It’s a fact that’s been true for decades, overlooked in the good times and surfaced when convenient. That Ireland had a housing boom that was intrinsically unsustainable was surely hardly news. The initial shock to Europe didn’t come from the discovery of these facts, it came from American mortgage markets. When European banks and other investors realized the extent of their losses, beginning in late 2008, they looked for ways to protect themselves and they did this as any sensible investor would, by selling the weak assets and buying strong ones: German, French bonds and above all United States treasuries. That is why yields rose on all the small peripheral countries and fell on the big ones despite the very different circumstances in the countries that were badly affected.
It’s obvious that Greece cannot implement the programs demanded of it without crashing its GDP, and driving up its debt to GDP ratio on that account. But even if it could, any event, affecting any European country, or for that matter, some place else in the world, could sink Greece again irrespective of what Greece does. So, there is no national policy solution and no financial market solution. That is the meaning of the negotiations now underway in Luxembourg and elsewhere. There will be a restructuring or a default, and there must be an economic and not merely a financial rescue. And beyond that there obviously must be not only a new European architecture, but a new financial architecture that is not built around the banks as they exist today and the credit markets as they came to exist in the period before the crisis. Either that or the depression in Europe will simply go on and on. Until eventually the European Union falls apart.
more

Middle class is disappearing faster than you can say IMF. The economy is shrinking at the same speed, yet the powers that be seem convinced that a country with a staggering debt will be saved with more an more … debt.
Civil liberties and work privileges are thrown out of every imaginable window, within or without the rule of law and the constitution.
The younger generation is condemned to pay for the greed of the older one by facing a bleak lack of any future.
Greeks have taken to the streets protesting against this opera buffa of prescribing the wrong medicine to the wrong patient, of implementing the wrong strategy to the wrong situation, the wrong solution to the wrong problem.
They are trying to find a map, a way out of and a meaning to this cacophony of economic gurus and evaluation houses and tons of CDS covering an unfathomable pile of pure junk.
They know that the debt that their elected government accumulates in their name is like a piece of rock tied in the neck of an amateur swimmer, bound to take him right to the bottom of the bottomless sea.
The people are breathing tear gas while the politicians and the bankers and the speculators and the corporations are getting closer for the kill. They breathe the smell of money and profit and fire sales.
At the same time my people have to face a racism so racist that makes racism a kindergarten play. All kind of insults are getting thrown on them, venomous stereotypes and ancient hate.
...

For the past 200 years, Greece has been at the forefront of Europe’s evolution.


