
Τετάρτη, Αυγούστου 31, 2011

Δευτέρα, Αυγούστου 29, 2011

Σάββατο, Αυγούστου 27, 2011

Τετάρτη, Αυγούστου 24, 2011

that was the river
these things you keep
you better throw them away
you wanna turn your back
on your soulless days
once you were tethered
but now you are free
once you were tethered
but now you are free
that was the river
this is the sea
if you're feelin' weary
or you been alone too long
or maybe you ve been sufferin' from
from a few too many
plans that have gone wrong
and you're tryin' to remember
how fine your life used to be
runnin' around banging your drum
like it's 1973
well that was the river
this is the sea
now you say you got trouble
you say you got pain
you say you got nothin' left to believe in
nothin' to hold on to
nothin to trust
nothin' but chains
you been scourin' your conscience
and rakin' through your memories
scourin' your conscience
rakin' through your memories
but that was the river
this is the sea
Now I can see you wavering
as you try to decide
you v got a war in your head
and it's tearin' you up inside
you're tryin' to make sense
of something that you just don't see
you're tryin' to make sense now
and you know that you once held the key
but that was the river...
this is the sea
yeah
Now I hear there's a train
it's comin' down the line
it's yours if you hurry
you got still enough time
you don't need no ticket
and you don't pay no fee
you don't need no ticket
and you don't pay no fee
that was the river
this is the sea

Τρίτη, Αυγούστου 23, 2011

Δευτέρα, Αυγούστου 22, 2011
remembering of things past

absolutely must for the brave of heart ... courtesy of my dear friend
μη πατήσεις το link αν είσαι ξενέρωτος


Σάββατο, Αυγούστου 20, 2011

ο αγαπημένος μου φίλος Κωστάκης

έκανε ένα συγκλονιστικό compilation με τους Pet Shop Boys
οπωσδήποτε ακούστε
copy paste
Παρασκευή, Αυγούστου 19, 2011


εικόνες από το τσίρκο της καταστροφής
ΜΟREThe Case Against Rating Agencies
By MICHAEL HUDSON
In today’s looming confrontation the ratings agencies are playing the political role of “enforcer” as the gatekeepers to credit, to put pressure on Iceland, Greece and even the United States to pursue creditor-oriented policies that lead inevitably to financial crises. These crises in turn force debtor governments to sell off their assets under distress conditions. In pursuing this guard-dog service to the world’s bankers, the ratings agencies are escalating a political strategy they have long been refined over a generation in the corrupt arena of local U.S. politics.
Why ratings agencies favor public selloffs rather than sound tax policy: The Kucinich Case Study
In 1936, as part of the New Deal’s reform of America’s financial markets, regulators forbid banks and institutional money managers to buy securities deemed “speculative” by “recognized rating manuals.” Insurance companies, pension funds and mutual funds subject to public regulation are required to “take into account” the views of the credit ratings agencies, provided them with a government-sanctioned monopoly. These agencies make their money by offering their “opinions” (for which they have never been legally liable) as to the payment prospects of various grades of security, from AAA (as secure government debt, the top rating because governments always can print the money to pay) down to various depths of junk.
Τρίτη, Αυγούστου 16, 2011
read

Σε έναν κόσμο...
... που περνιέται για ενάρετος, κάθε αμαρτωλός χαίρεται να βλέπει γύρω του κι άλλους σαν κι αυτόν. Επειδή όσο περισσότεροι γίνονται οι αμαρτωλοί τόσο περισσότερο από το βάρος της αμαρτίας τους φεύγει από τα κεφάλια τους και πέφτει στο κεφάλι του Δημιουργού τους. Ωστε η Ελλάδα δεν ήταν λοιπόν μια «ειδική περίπτωση».
Οι ομοιότητες...
... είναι ειρωνικές. Τα μέτρα που λαμβάνει η Ιταλία (και μάλιστα χωρίς ΔΝΤ), τώρα που νιώθει κι αυτή στον σβέρκο της την καυτή ανάσα των αγορών, σίγουρα μας θυμίζουν κάτι: περικοπές 8,5 δισ. ευρώ στις δαπάνες των υπουργείων έως το 2013, περικοπές 9,5 δισ. ευρώ στην Τοπική Αυτοδιοίκηση έως το 2013, εξοικονόμηση 1 δισ. ευρώ από τις συντάξεις το 2012, αύξηση της ηλικίας συνταξιοδότησης των γυναικών από τα 60 στα 65 χρόνια, παρακράτηση ποσού από τα ασφαλιστικά ταμεία του Δημοσίου έως και δύο χρόνια μετά τη συνταξιοδότηση των δικαιούχων, μείωση του κόστους του πολιτικού προσωπικού, κατάργηση 34 από τις 110 περιφερειακές κυβερνήσεις και συγχώνευση μικρών δήμων, φόρος αλληλεγγύης 5% και 10% για τα υψηλά εισοδήματα, αγορές άνω των 2.500 ευρώ μόνο μέσω τραπέζης, μεταφορά των μη θρησκευτικών επίσημων αργιών τις Κυριακές, απελευθέρωση της αγοράς εργασίας με επιχειρησιακές συμβάσεις. Και όλα αυτά γιατί; Επειδή συνέβη το απευκταίο: η Ιταλία και η Ισπανία δανείζονται σήμερα ακριβότερα από την Ελλάδα, την Ιρλανδία και την Πορτογαλία.
Οσο θα συνεχίζονται...
... οι επιθέσεις των αγορών εναντίον της Ιταλίας και της Ισπανίας (και αύριο της Γαλλίας) τόσο αυτές οι χώρες θα δυσκολεύονται να δίνουν δισεκατομμύρια στο ταμείο χρηματοπιστωτικής σταθερότητας για να δανείζονται φθηνότερα οι περιφερειακές χώρες του ευρώ. Γιατί συνέβη το απευκταίο; Επειδή οι οίκοι πιστοληπτικής αξιολόγησης κάνουν τη δουλειά τους: προστατεύουν τους κερδοσκόπους που υπηρετούν. Οποτε οι κυβερνήσεις ζητούν από αυτούς τους «επενδυτές» να απορροφήσουν κάποιες από τις ζημιές που προκάλεσε η κερδοσκοπία τους, οι οίκοι αξιολόγησης κάνουν στις κυβερνήσεις μια προσφορά που αυτές δύσκολα μπορούν να αρνηθούν: ή αφήνετε ήσυχους τους «επενδυτές» ή θάβουμε τα ομόλογά σας. Οι οίκοι δεν κάνουν οικονομία αλλά πολιτική, από τότε που εκχώρησαν σε αυτούς την πολιτική οι κυβερνήσεις. Το σχέδιο αυτής της πολιτικής είναι ένα, λέει ο οικονομολόγος Στιβ Κιν: «η μεγαλύτερη μεταβίβαση πλούτου στην Ιστορία», καθώς αυτοί οι «επενδυτές» φορτώνουν τις ζημιές τους στις χώρες και στους λαούς τους. Μια απύθμενη άβυσσος καταπίνει τα έσοδα ατόμων, επιχειρήσεων, πόλεων, ολόκληρων κρατών, για να καταλήξουν στις τσέπες των κερδοσκόπων. Γι' αυτό η λιτότητα που εφαρμόζουν οι χώρες, μεγάλες ή μικρές, ενάρετες ή αμαρτωλές, είναι πανομοιότυπη. Επειδή υπάρχει σχέδιο.
Το σχέδιο...
... αυτό, όμως, που οι Δημιουργοί του ευρώ επιβάλλουν πιο φανατικά από όλους, καταστρέφει σήμερα ένα άλλο, όπως γράφει το «Kantoos Economics»: «Ενα από τα πιο συναρπαστικά σχέδια στην ανθρώπινη Ιστορία, την ενότητα και τη φιλία των χωρών της Ευρώπης».
LAURA LEVINE
 Madonna, New York City, 1982
In 1982 I was assigned to photograph Madonna for Interview magazine. Her very first single (“Everybody”) was about to be released and no one really knew what she looked like. She (like most of my photo subjects back then) arrived alone, climbing the four flights to my small Chinatown apartment. She was very professional and easy to work with. Even when I asked her to do seemingly ridiculous things, like wrap herself in my curtains and pretend to scream.

Δευτέρα, Αυγούστου 15, 2011
nouvelle vague
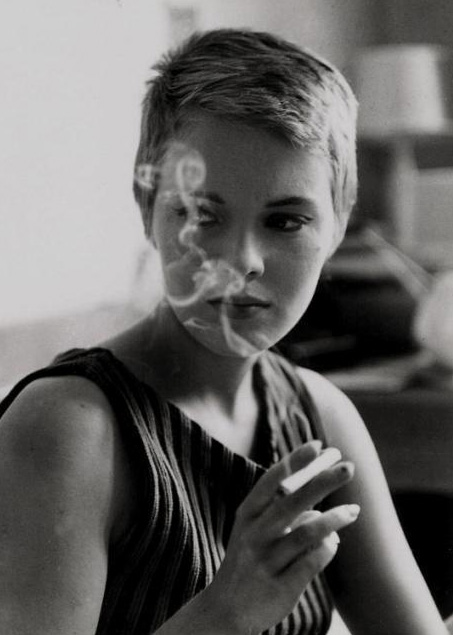
The exquisitely beautiful Jean Seberg in BREATHLESS (1960)

BREATHLESS (1960)

Anouk Aimée in Jacques Demy's LOLA (1961)

Francois Truffaut filming STOLEN KISSES (1968) on location

Truffaut with Françoise Dorléac on the set of THE SOFT SKIN (1964)

Jean Luc Godard (left) filming UNE FEMME EST UNE FEMME (1961)
marx was right? πάρε μου τηλέφωνο την Αλέκα
Roubini: Marx was right. Capitalism may be destroying itself.
Nouriel Roubini is a mainstream economist who teaches at New York University and may be best known as one of the early predictors of the '08 crash.
He is no Marxist.
But in an interview with the Wall Street Journal, Roubini admitted that Marx was right about Capitalism and raised the possibility that Capitalism is destroying itself in the way Marx outlined more than a century and a half ago.
WSJ: So you painted a bleak picture of sub-par economic growth going forward, with an increased risk of another recession in the near future. That sounds awful. What can government and what can businesses do to get the economy going again or is it just sit and wait and gut it out?Roubini: Businesses are not doing anything. They're not actually helping. All this risk made them more nervous. There's a value in waiting. They claim they're doing cutbacks because there's excess capacity and not adding workers because there's not enough final demand, but there's a paradox, a Catch-22. If you're not hiring workers, there's not enough labor income, enough consumer confidence, enough consumption, not enough final demand. In the last two or three years, we've actually had a worsening because we've had a massive redistribution of income from labor to capital, from wages to profits, and the inequality of income has increased and the marginal propensity to spend of a household is greater than the marginal propensity of a firm because they have a greater propensity to save, that is firms compared to households. So the redistribution of income and wealth makes the problem of inadequate aggregate demand even worse.
Karl Marx had it right. At some point, Capitalism can destroy itself. You cannot keep on shifting income from labor to Capital without having an excess capacity and a lack of aggregate demand. That's what has happened. We thought that markets worked. They're not working. The individual can be rational. The firm, to survive and thrive, can push labor costs more and more down, but labor costs are someone else's income and consumption. That's why it's a self-destructive process.
The full interview is here.
The portion where Roubini talks about Marx and excess capacity is here.
Σάββατο, Αυγούστου 13, 2011

Πέμπτη, Αυγούστου 11, 2011

Δευτέρα, Αυγούστου 08, 2011
Διορθώστε με αν κάνω λάθος

Οι τράπεζες, οι οίκοι αξιολόγησης (της ανοχής μας;), τα χρηματιστήρια, οι αγορές, οι σπεκουλαδόροι, τα λαμόγια , τα δομημένα ομόλογα, τα ασφάλιστρα κινδύνου, τα μοντέρνα οικονομικά προϊόντα, οι οικονομολόγοι του κώλου, τα στοιχήματα πάνω σε οικονομίες που καταρρέουν, η ύβρις, η απληστία και ο Μαμωνάς οδήγησαν την υφήλιο σε μια άνευ προηγουμένου οικονομική κρίση στην οποία χώνεται κάθε μέρα όλο και πιο βαθιά
και παρ όλα αυτά
Οι τράπεζες, οι οίκοι αξιολόγησης (της ανοχής μας;), τα χρηματιστήρια, οι αγορές, οι σπεκουλαδόροι, τα λαμόγια , τα δομημένα ομόλογα, τα ασφάλιστρα κινδύνου, τα μοντέρνα οικονομικά προϊόντα, οι οικονομολόγοι του κώλου, τα στοιχήματα πάνω σε οικονομίες που καταρρέουν, η ύβρις, η απληστία και ο Μαμωνάς απαιτούν και εφαρμόζονται απάνθρωπες πολιτικές λιτότητας, με εκατοντάδες χιλιάδες ανθρώπους να χάνουν καθημερινά τις δουλειές τους, απαιτούν απολύσεις και επιβάλουν την πολιτική τους την ίδια στιγμή που καταγράφουν τεράστια κέρδη ενώ όλοι οι άλλοι καταγράφουν συντριπτικές απώλειες.
Κι όλα αυτά αφού έχουν εκβιαστικά – με την περίφημη δικαιολογία «είμαστε πολύ μεγάλοι για ν αποτύχουμε» - απομυζήσει τρισεκατομμύρια ευρώ από τους φορολογούμενους σε πακέτα διάσωσης που κάνουν το ελληνικό μνημόνιο να μοιάζει με γλειφιτζούρι.
Κάτι δεν πάει καλά
Κυριακή, Αυγούστου 07, 2011
the art of falling apart
I say incurable. This is the diagnosis of an irreversible disease. The corruption and collapse of the rule of law, in the financial sphere, is basically irreparable. It’s not just that restoring trust takes a long time. It’s that under the new technological order in this field, it can not be done. The technologies are designed to sow and foster distrust and that is the consequence of using them. The recent experience proves this, it seems to me. And therefore there can be no return to the way things were before. In other words, we are at the end of the illusion of a market place in the financial sphere.
Let me take this analysis and bring it to bear momentarily on Europe. We speak in a common place way these days of the Greek crisis, the Irish crisis, the Portuguese crisis and so forth, as though these were distinct financial events. This fosters the impression that each can be resolved by appropriate agreement between the creditors, headquartered in Frankfurt, Brussels, Berlin, Paris, and the debtors taken one by one. Good behavior, taking the form of a suitable austerity will be rewarded by a return to normal credit conditions and market access. That, at least, is the official presumption. The financial market, in this imagery, is severe but fair, she cracks the whip on the profligate but praises and rewards the prim.
But that Greece has a weak tax system and a big civil service was hardly news. It’s a fact that’s been true for decades, overlooked in the good times and surfaced when convenient. That Ireland had a housing boom that was intrinsically unsustainable was surely hardly news. The initial shock to Europe didn’t come from the discovery of these facts, it came from American mortgage markets. When European banks and other investors realized the extent of their losses, beginning in late 2008, they looked for ways to protect themselves and they did this as any sensible investor would, by selling the weak assets and buying strong ones: German, French bonds and above all United States treasuries. That is why yields rose on all the small peripheral countries and fell on the big ones despite the very different circumstances in the countries that were badly affected.
It’s obvious that Greece cannot implement the programs demanded of it without crashing its GDP, and driving up its debt to GDP ratio on that account. But even if it could, any event, affecting any European country, or for that matter, some place else in the world, could sink Greece again irrespective of what Greece does. So, there is no national policy solution and no financial market solution. That is the meaning of the negotiations now underway in Luxembourg and elsewhere. There will be a restructuring or a default, and there must be an economic and not merely a financial rescue. And beyond that there obviously must be not only a new European architecture, but a new financial architecture that is not built around the banks as they exist today and the credit markets as they came to exist in the period before the crisis. Either that or the depression in Europe will simply go on and on. Until eventually the European Union falls apart.
more
Πέμπτη, Αυγούστου 04, 2011


Τετάρτη, Αυγούστου 03, 2011


Δευτέρα, Αυγούστου 01, 2011
big time good music
...
http://www.mixcloud.com/dc-kostas/music-to-play-cards-to/?ref=nf#utm_source=facebook&utm_medium=share_button&utm_campaign=cloudcast_page
http://www.mixcloud.com/dc-kostas/music-to-play-cards-to/?ref=nf#utm_source=facebook&utm_medium=share_button&utm_campaign=cloudcast_page
Εγγραφή σε:
Αναρτήσεις (Atom)